
May 2, 2026 · by BalayHub Admin · 6 min read
How Climate Change Is Affecting Philippine Property Values
Climate change and Philippine property values: Manila sea level rising 2.6 cm a year, flood and liquefaction zones, insurance rates, checks before buying.
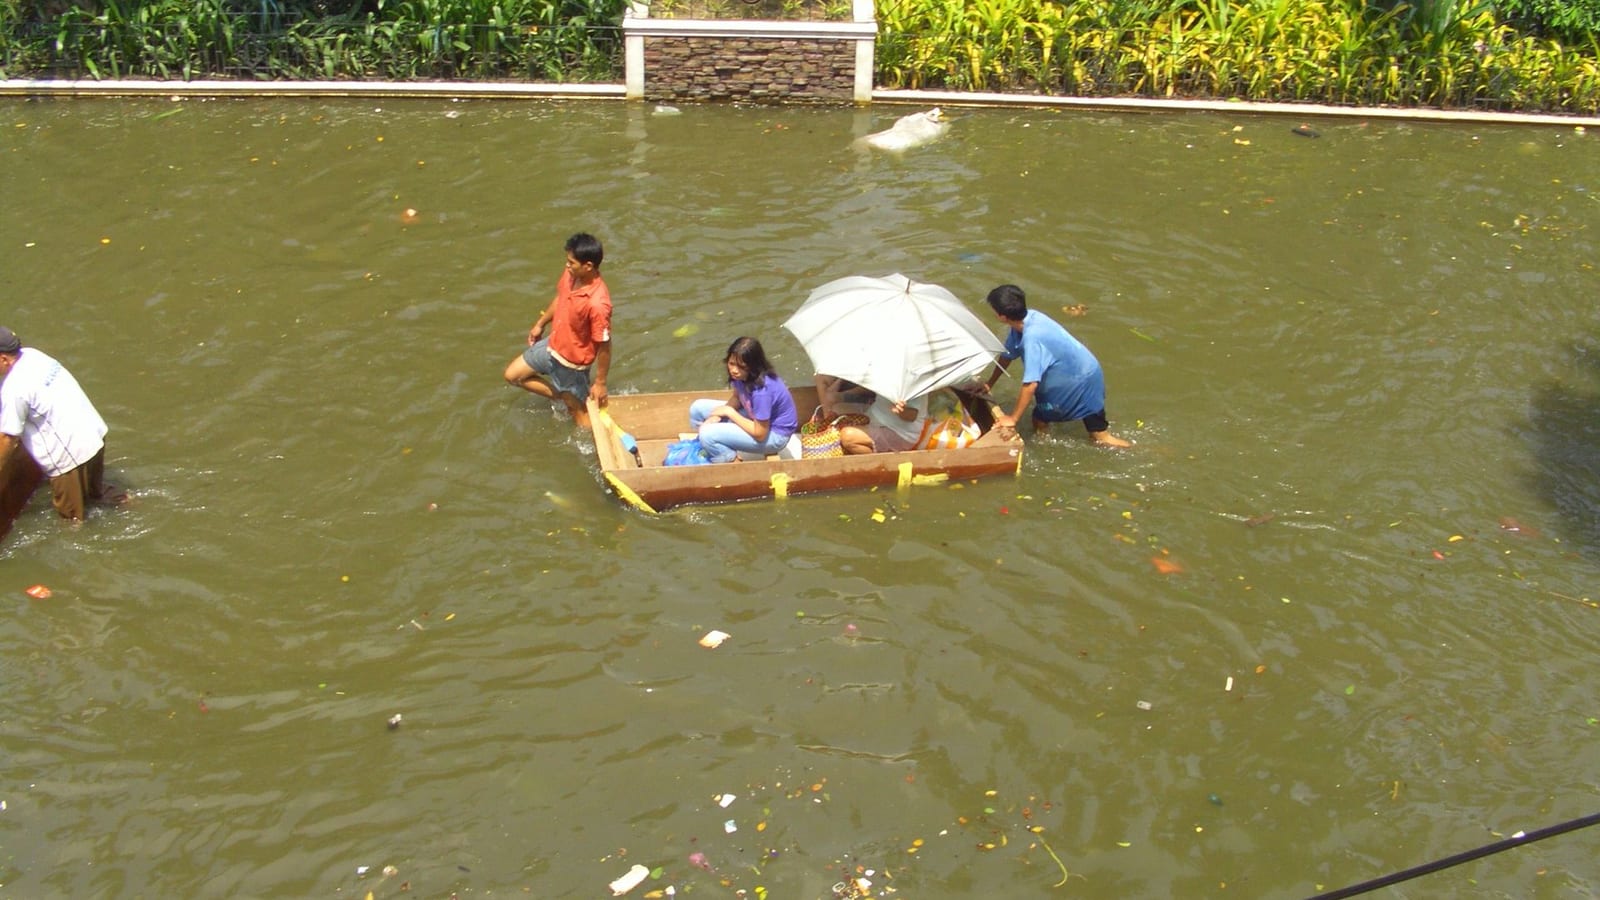
Climate risk and Philippine property values are now tied together by numbers that a buyer can look up. The government's own climate assessment, included in the National Adaptation Plan approved in 2024, puts the sea level at Manila rising by about 2.6 centimeters a year, against 1.3 millimeters a year in the 1900s, and attributes most of the rise to land subsidence from groundwater pumping rather than to the ocean itself. Fewer than one household in five holds any disaster insurance on its property, and the country lost about ₱911 billion (about $1.45e+04 million / €1.3e+04 million) to natural disasters between 2000 and 2023 by one Senate committee count. None of that sets a price on a specific house. What it does is change the questions a buyer should ask, and this guide sets them out: where the water goes, what the land under a building is doing, what insurance costs, and how to check a specific address before paying for it.
Sea level and sinking ground
The 2.6 centimeters a year is a Manila figure, measured at the tide gauge, and it is roughly twenty times the historical rate mainly because the ground is going down, not because the water is coming up faster. The assessment links the subsidence zones to heavy groundwater use, and the satellite data behind it show the same link in MIMAROPA, Central Luzon, Central Visayas and the Davao region. The trend is not uniform: Legazpi and Davao show gradual rises, and no clear trend was found for Cebu or Jolo.
The exposure estimates in the plan are the ones to keep in mind when a coastal or reclaimed lot is offered as an investment: a one meter rise would affect about 7,000 square kilometers, 1.8 million people and 2,490 barangays. For Metro Manila the practical reading is that the low lying belt along Manila Bay, the Caloocan, Malabon, Navotas and Valenzuela corridor that our flood guide describes as living with tidal flooding and slow drainage, is the area where the long term trend works against the owner, while the Diliman ridge, the Antipolo foothills just east of the metro and the higher parts of Muntinlupa and Las Piñas sit well above it.
Reclaimed and delta ground carries a second risk in the same places. PHIVOLCS flags low lying, reclaimed and coastal areas of the metro as prone to liquefaction in a strong earthquake, which our earthquake risk guide maps district by district.
Floods and the value of elevation
Flooding is the climate risk that shows up every rainy season and the one buyers price most readily. Two properties a few streets apart can have different flood histories, because elevation is only half of the story; drainage, creeks and the river valleys of the Pasig, the Marikina and the Tullahan decide the rest. The Marikina River valley carries the metro's best known flood history, and the KAMANAVA belt its tidal one, but Marikina also has high, dry neighborhoods and Quezon City has creekside streets that pool.
We do not publish a discount for flood risk, because our listing sample cannot separate it from the other reasons two homes differ in price, and a listing rarely states its flood history at all. The buyer has to establish it, and the way to do that is in our guide on how to check if a property floods: HazardHunterPH gives a hazard assessment for the exact pin, Project NOAH shows modeled flood depth for 5 year, 25 year and 100 year rain, and the barangay and the neighbors remember the last three storms better than any map.
What insurance costs, and what it says
The Insurance Commission's minimum rates for property cover are small: typhoon and flood cover from 0.05% of the sum insured a year, earthquake cover from 0.10%, with a mandatory 2% deductible on typhoon and flood claims. On a ₱2,000,000 (about $31,900 / €28,500) house that is about ₱1,000 (about $16 / €14) a year for flood and typhoon and ₱2,000 (about $32 / €28) for earthquake at the minimum, and more in coastal and flood prone areas, where insurers price the exposure. Fewer than 20% of households carry any of it, according to Insurance Commission data cited in late 2025.
For a buyer the premium is a signal as much as a cost. A quote that comes back high, with exclusions or a larger deductible for a particular street, is an underwriter's reading of the risk the seller did not mention. Our guide to home insurance in the Philippines explains what the standard fire policy excludes and how the typhoon, flood and earthquake extensions are added, and our guide to condo insurance covers the split between the building's policy and the unit owner's.
Coastal property
A beach lot carries the sea level trend, storm surge and erosion on top of the rules that already limit it: the foreshore belongs to the State and a public easement runs along the shore inside every titled lot, so part of the parcel stays open and unbuilt. Our guide to beachfront property sets out the easement widths and the foreshore rules, and our guide to a vacation home in the Philippines weighs the coast against the ridge and the mountains on upkeep and risk. The practical checks are the same as for any lot, plus two: the storm surge and erosion history of that stretch of coast from the barangay and the municipal disaster office, and a resale question that is easy to forget, which is who will buy a shoreline lot in fifteen years and on what terms.
How to put it into a decision
Run the hazard check before the viewing, not after. Ask the seller for the flood history in writing, and compare it with what the neighbors say. Get an insurance quote for the specific address before the offer and treat a refusal or a loaded premium as information. Price elevation, drainage and a reliable power supply as features worth paying for, because tenants do, and a condo that stands through a storm with the streets around it under water still loses the tenant. And for a long hold, prefer ground that is not sinking: the government's figures on subsidence are the clearest climate signal in Philippine property, and the one least often discussed at a showroom.
This article is general information, not investment advice. Figures are from the sources named as of October 2026; hazard and insurance conditions are specific to each address, so check them for the property you are considering.
Last updated 14 October 2026.
Dollar and euro figures are approximate conversions at ₱62.8 per US dollar and ₱70.2 per euro (ECB reference rates, 2026-10-13).
Frequently asked questions
Is climate change already affecting Philippine property values?
The clearest measured change is physical rather than priced: the government's climate assessment in the 2024 National Adaptation Plan puts Manila's sea level rise at about 2.6 centimeters a year, mostly from land subsidence, and a one meter rise would affect 7,000 square kilometers and 1.8 million people. We do not publish a flood discount, because listing prices cannot isolate it, but buyers now check hazard maps and insurers price the exposure address by address.
How do I check flood and hazard risk before buying property?
Use HazardHunterPH from DOST and PHIVOLCS, which generates a flood, landslide and earthquake assessment for an exact address or pin, and Project NOAH, which shows modeled flood depth for 5 year, 25 year and 100 year rain. Then ask the barangay and the neighbors about the last three storms, request the flood history from the seller in writing, and get an insurance quote for the specific address before making an offer.
Are beachfront properties in the Philippines still a good investment?
They carry the sea level trend, storm surge and erosion on top of rules that already limit them: the foreshore belongs to the State and a public easement runs along the shore inside every titled lot. Before buying, get the storm surge and erosion history of that stretch of coast from the barangay and the municipal disaster office, confirm the easement on the survey, and consider who will buy a shoreline lot in fifteen years.
How much does flood and typhoon insurance cost in the Philippines?
The Insurance Commission's minimum annual rates are 0.05% of the sum insured for typhoon and flood cover and 0.10% for earthquake cover, with a mandatory 2% deductible on typhoon and flood claims, so a ₱2,000,000 (about $31,900 / €28,500) house pays about ₱1,000 and ₱2,000 (about $16 to $32 / €14 to €28) a year at the minimum. Rates run higher in coastal and flood prone areas, and fewer than 20% of households carry any disaster cover at all.
Ang climate risk at ang halaga ng mga property sa Pilipinas ay magkaugnay na ngayon sa pamamagitan ng mga numerong kayang hanapin ng isang buyer. Ang sariling climate assessment ng gobyerno, na kasama sa National Adaptation Plan na inaprubahan noong 2024, ay nagsasabing tumataas ang sea level sa Manila nang humigit-kumulang 2.6 centimeters kada taon, kumpara sa 1.3 millimeters kada taon noong 1900s, at iniuugnay ang malaking bahagi ng pagtaas sa land subsidence dahil sa groundwater pumping, hindi sa dagat mismo. Wala pang isa sa bawat limang household ang may anumang disaster insurance sa kanilang property, at nawalan ang bansa ng humigit-kumulang ₱911 billion (mga $1.45e+04 million / €1.3e+04 million) dahil sa mga natural disaster sa pagitan ng 2000 at 2023 ayon sa bilang ng isang komite ng Senado. Wala sa mga ito ang nagtatakda ng presyo ng isang partikular na bahay. Ang binabago nito ay ang mga tanong na dapat itanong ng isang buyer, at inilalatag ng gabay na ito ang mga iyon: saan pumupunta ang tubig, ano ang nangyayari sa lupang kinatatayuan ng isang gusali, magkano ang insurance, at paano i-check ang isang partikular na address bago ito bayaran.
Sea level at lumulubog na lupa
Ang 2.6 centimeters kada taon ay numero para sa Manila, na sinukat sa tide gauge, at halos dalawampung beses ito ng historical rate pangunahin dahil bumababa ang lupa, hindi dahil mas mabilis na tumataas ang tubig. Iniuugnay ng assessment ang mga subsidence zone sa matinding paggamit ng groundwater, at ipinapakita ng satellite data sa likod nito ang parehong ugnayan sa MIMAROPA, Central Luzon, Central Visayas at Davao region. Hindi pare-pareho ang trend: nagpapakita ng unti-unting pagtaas ang Legazpi at Davao, at walang malinaw na trend na natagpuan para sa Cebu o Jolo.
Ang mga exposure estimate sa plano ang dapat tandaan kapag inaalok bilang investment ang isang coastal o reclaimed na lote: ang pagtaas ng isang metro ay makakaapekto sa humigit-kumulang 7,000 square kilometers, 1.8 million na tao at 2,490 barangay. Para sa Metro Manila, ang praktikal na pagbasa ay ito: ang mababang lupain sa kahabaan ng Manila Bay, ang koridor ng Caloocan, Malabon, Navotas at Valenzuela na inilalarawan ng aming gabay sa flood bilang lugar na nabubuhay kasama ang tidal flooding at mabagal na drainage, ang lugar kung saan kumokontra sa may-ari ang pangmatagalang trend, habang ang Diliman ridge, ang paanan ng bundok sa Antipolo sa silangan mismo ng metro at ang mas matataas na bahagi ng Muntinlupa at Las Piñas ay nasa mas mataas na posisyon.
May pangalawang panganib ang reclaimed at delta na lupa sa parehong mga lugar. Tinutukoy ng PHIVOLCS ang mababa, reclaimed at coastal na mga bahagi ng metro bilang prone sa liquefaction sa isang malakas na lindol, na minamapa ng aming gabay sa earthquake risk distrito por distrito.
Baha at ang halaga ng elevation
Ang baha ang climate risk na lumilitaw tuwing tag-ulan at ang pinakamadaling isinasama ng mga buyer sa presyo. Dalawang property na ilang kalye lang ang layo sa isa't isa ay maaaring magkaiba ng flood history, dahil kalahati lang ng kuwento ang elevation; ang drainage, ang mga creek at ang mga lambak-ilog ng Pasig, Marikina at Tullahan ang nagpapasya sa natitira. Ang lambak ng Marikina River ang may pinakakilalang flood history sa metro, at ang KAMANAVA belt naman ang may tidal flooding, pero may matataas at tuyong mga neighborhood din ang Marikina at may mga kalye sa tabi ng creek sa Quezon City na naiipunan ng tubig.
Hindi kami naglalathala ng discount para sa flood risk, dahil hindi kayang ihiwalay ng aming listing sample ang epekto nito mula sa iba pang dahilan kung bakit magkaiba ang presyo ng dalawang bahay, at bihirang banggitin ng isang listing ang flood history nito. Ang buyer ang kailangang mag-alam nito, at ang paraan ay nasa aming gabay kung paano i-check kung bumabaha sa isang property: nagbibigay ang HazardHunterPH ng hazard assessment para sa eksaktong pin, ipinapakita ng Project NOAH ang modeled na lalim ng baha para sa 5 year, 25 year at 100 year na ulan, at mas naaalala ng barangay at ng mga kapitbahay ang huling tatlong bagyo kaysa sa anumang mapa.
Magkano ang insurance, at ano ang sinasabi nito
Maliit ang minimum rates ng Insurance Commission para sa property cover: typhoon at flood cover mula 0.05% ng sum insured kada taon, earthquake cover mula 0.10%, na may mandatory na 2% deductible sa mga typhoon at flood claim. Sa isang bahay na ₱2,000,000 (mga $31,900 / €28,500), iyan ay humigit-kumulang ₱1,000 (mga $16 / €14) kada taon para sa flood at typhoon at ₱2,000 (mga $32 / €28) para sa earthquake sa minimum, at mas mataas sa coastal at flood prone na mga lugar, kung saan pinepresyuhan ng mga insurer ang exposure. Wala pang 20% ng mga household ang may alinman dito, ayon sa datos ng Insurance Commission na binanggit noong huling bahagi ng 2025.
Para sa buyer, ang premium ay senyales at hindi lang gastos. Ang quote na mataas ang balik, na may mga exclusion o mas malaking deductible para sa isang partikular na kalye, ay pagbasa ng underwriter sa panganib na hindi binanggit ng seller. Ipinapaliwanag ng aming gabay sa home insurance sa Pilipinas kung ano ang hindi sakop ng standard fire policy at paano idinadagdag ang typhoon, flood at earthquake extension, at sinasaklaw ng aming gabay sa condo insurance ang hatian sa pagitan ng policy ng gusali at ng policy ng may-ari ng unit.
Coastal property
Dala ng isang beach lot ang sea level trend, storm surge at erosion bukod pa sa mga patakarang naglilimita na rito: pag-aari ng Estado ang foreshore at may public easement na tumatakbo sa kahabaan ng dalampasigan sa loob ng bawat lote na may titulo, kaya may bahagi ng parcel na mananatiling bukas at hindi matatayuan. Inilalatag ng aming gabay sa beachfront property ang mga lapad ng easement at ang mga patakaran sa foreshore, at tinitimbang ng aming gabay sa vacation home sa Pilipinas ang baybayin laban sa ridge at sa kabundukan pagdating sa maintenance at panganib. Pareho ang mga praktikal na check gaya ng sa anumang lote, dagdag ang dalawa: ang storm surge at erosion history ng bahaging iyon ng baybayin mula sa barangay at sa municipal disaster office, at isang tanong tungkol sa resale na madaling makalimutan, kung sino ang bibili ng shoreline na lote pagkalipas ng labinlimang taon at sa anong mga kondisyon.
Paano ito isama sa desisyon
Gawin ang hazard check bago ang viewing, hindi pagkatapos. Hingin sa seller ang flood history nang nakasulat, at ikumpara ito sa sinasabi ng mga kapitbahay. Kumuha ng insurance quote para sa partikular na address bago mag-offer at ituring na impormasyon ang pagtanggi o ang mabigat na premium. Ituring ang elevation, drainage at maaasahang supply ng kuryente bilang mga feature na sulit bayaran, dahil ganoon ang ginagawa ng mga tenant, at ang condo na nakatayo pa rin pagkatapos ng bagyo habang nakalubog sa tubig ang mga kalye sa paligid nito ay mawawalan pa rin ng tenant. At para sa pangmatagalang hawak, piliin ang lupang hindi lumulubog: ang mga numero ng gobyerno tungkol sa subsidence ang pinakamalinaw na climate signal sa property sa Pilipinas, at ang pinakabihirang pag-usapan sa isang showroom.
Pangkalahatang impormasyon ang artikulong ito, hindi payo sa pamumuhunan. Ang mga numero ay mula sa mga pinagmulang binanggit noong Oktubre 2026; partikular sa bawat address ang mga kondisyon ng hazard at insurance, kaya i-check ang mga ito para sa property na iyong isinasaalang-alang.
Huling na-update noong 14 Oktubre 2026.
Tinatayang conversion lang ang mga halaga sa dollar at euro, sa ₱62.8 kada US dollar at ₱70.2 kada euro (ECB reference rates, 2026-10-13).
Mga madalas itanong
Naaapektuhan na ba ng climate change ang halaga ng mga property sa Pilipinas?
Ang pinakamalinaw na nasukat na pagbabago ay pisikal, hindi sa presyo: ang climate assessment ng gobyerno sa 2024 National Adaptation Plan ay nagtatakda ng pagtaas ng sea level sa Manila sa humigit-kumulang 2.6 centimeters kada taon, karamihan dahil sa land subsidence, at ang pagtaas ng isang metro ay makakaapekto sa 7,000 square kilometers at 1.8 million na tao. Hindi kami naglalathala ng flood discount, dahil hindi ito kayang ihiwalay ng mga presyo ng listing, pero nag-che-check na ngayon ang mga buyer ng hazard map at pinepresyuhan ng mga insurer ang exposure bawat address.
Paano ko i-check ang flood at hazard risk bago bumili ng property?
Gamitin ang HazardHunterPH mula sa DOST at PHIVOLCS, na gumagawa ng flood, landslide at earthquake assessment para sa eksaktong address o pin, at ang Project NOAH, na nagpapakita ng modeled na lalim ng baha para sa 5 year, 25 year at 100 year na ulan. Pagkatapos, tanungin ang barangay at ang mga kapitbahay tungkol sa huling tatlong bagyo, hingin sa seller ang flood history nang nakasulat, at kumuha ng insurance quote para sa partikular na address bago mag-offer.
Maganda pa bang investment ang mga beachfront property sa Pilipinas?
Dala nila ang sea level trend, storm surge at erosion bukod pa sa mga patakarang naglilimita na sa kanila: pag-aari ng Estado ang foreshore at may public easement na tumatakbo sa kahabaan ng dalampasigan sa loob ng bawat lote na may titulo. Bago bumili, kunin ang storm surge at erosion history ng bahaging iyon ng baybayin mula sa barangay at sa municipal disaster office, kumpirmahin ang easement sa survey, at isaalang-alang kung sino ang bibili ng shoreline na lote pagkalipas ng labinlimang taon.
Magkano ang flood at typhoon insurance sa Pilipinas?
Ang minimum na taunang rates ng Insurance Commission ay 0.05% ng sum insured para sa typhoon at flood cover at 0.10% para sa earthquake cover, na may mandatory na 2% deductible sa mga typhoon at flood claim, kaya ang isang bahay na ₱2,000,000 (mga $31,900 / €28,500) ay nagbabayad ng humigit-kumulang ₱1,000 at ₱2,000 (mga $16 hanggang $32 / €14 hanggang €28) kada taon sa minimum. Mas mataas ang rates sa coastal at flood prone na mga lugar, at wala pang 20% ng mga household ang may anumang disaster cover.
Ang climate risk ug ang presyo sa mga property sa Pilipinas konektado na karon pinaagi sa mga numero nga mahimong susihon sa usa ka buyer. Ang kaugalingong climate assessment sa gobyerno, nga gilakip sa National Adaptation Plan nga giaprobahan niadtong 2024, nag-ingon nga ang sea level sa Manila mosaka og mga 2.6 centimeters matag tuig, kumpara sa 1.3 millimeters matag tuig niadtong 1900s, ug gipasabot nga ang kadaghanan sa pagsaka tungod sa land subsidence gikan sa groundwater pumping, dili tungod sa dagat mismo. Wala pay usa sa lima ka panimalay ang adunay disaster insurance sa ilang property, ug ang nasod nawad-an og mga ₱911 billion (mga $1.45e+04 million / €1.3e+04 million) tungod sa natural disasters tali sa 2000 ug 2023 sumala sa ihap sa usa ka Senate committee. Wala niini ang magtakda og presyo sa usa ka piho nga balay. Ang gibuhat niini mao ang pag-usab sa mga pangutana nga angay ipangutana sa usa ka buyer, ug kini nga giya naglista niini: asa moadto ang tubig, unsa ang nahitabo sa yuta ilalom sa usa ka building, pila ang gasto sa insurance, ug unsaon pag-check ang usa ka piho nga address sa dili pa kini bayran.
Sea level ug ang nagkaunlod nga yuta
Ang 2.6 centimeters matag tuig usa ka numero sa Manila, gisukod sa tide gauge, ug mga kawhaan ka pilo kini sa historical rate labi na tungod kay ang yuta nagkaunlod, dili tungod kay mas paspas ang pagsaka sa tubig. Gikonektar sa assessment ang mga subsidence zone sa grabe nga paggamit sa groundwater, ug ang satellite data luyo niini nagpakita sa samang koneksyon sa MIMAROPA, Central Luzon, Central Visayas ug sa Davao region. Dili parehas ang trend sa tanang lugar: ang Legazpi ug Davao nagpakita og hinay-hinay nga pagsaka, ug walay klarong trend nga nakita sa Cebu o Jolo.
Ang mga exposure estimate sa plano mao ang angay hinumdoman kon ang usa ka coastal o reclaimed nga lote gitanyag isip investment: ang usa ka metro nga pagsaka makaapekto og mga 7,000 square kilometers, 1.8 million ka tawo ug 2,490 ka barangay. Para sa Metro Manila, ang praktikal nga pagsabot mao nga ang ubos nga bahin daplin sa Manila Bay, ang Caloocan, Malabon, Navotas ug Valenzuela corridor nga gihulagway sa among flood guide nga nagpuyo uban sa tidal flooding ug hinay nga drainage, mao ang lugar diin ang long term trend mosupak sa tag-iya, samtang ang Diliman ridge, ang Antipolo foothills sa sidlakan ra sa metro ug ang mas taas nga bahin sa Muntinlupa ug Las Piñas naa sa mas taas kaayo niini.
Ang reclaimed ug delta nga yuta adunay ikaduhang risgo sa samang mga lugar. Gimarkahan sa PHIVOLCS ang ubos, reclaimed ug coastal nga mga lugar sa metro isip prone sa liquefaction kon adunay kusog nga linog, nga gimapa sa among earthquake risk guide sa matag distrito.
Flood ug ang bili sa elevation
Ang flood mao ang climate risk nga makita matag tingulan ug mao ang labing dali nga gipresyohan sa mga buyer. Duha ka property nga pipila lang ka kalye ang gilay-on mahimong adunay lahi nga flood history, tungod kay ang elevation katunga lang sa istorya; ang drainage, ang mga sapa ug ang mga river valley sa Pasig, Marikina ug Tullahan ang modesisyon sa nahibilin. Ang Marikina River valley ang adunay labing nailhan nga flood history sa metro, ug ang KAMANAVA belt ang adunay tidal nga flood history, apan ang Marikina aduna usab mga taas ug uga nga kasilinganan ug ang Quezon City adunay mga kalye daplin sa sapa nga mapundo ang tubig.
Wala kami mag-publish og discount para sa flood risk, tungod kay ang among listing sample dili makabulag niini gikan sa ubang mga rason nganong lahi ang presyo sa duha ka balay, ug ang usa ka listing panagsa ra kaayo magsulti sa flood history niini. Ang buyer ang kinahanglang mag-establisar niini, ug ang paagi sa pagbuhat niana naa sa among giya kon unsaon pag-check kon mabahaan ba ang usa ka property: ang HazardHunterPH naghatag og hazard assessment para sa eksaktong pin, ang Project NOAH nagpakita sa modeled flood depth para sa 5 year, 25 year ug 100 year nga ulan, ug ang barangay ug ang mga silingan mas nakahinumdom sa kataposang tulo ka bagyo kaysa bisan unsang mapa.
Pila ang gasto sa insurance, ug unsa ang gipasabot niini
Gamay ra ang minimum rates sa Insurance Commission para sa property cover: ang typhoon ug flood cover sugod sa 0.05% sa sum insured matag tuig, ang earthquake cover sugod sa 0.10%, nga adunay mandatory nga 2% deductible sa mga typhoon ug flood claim. Sa usa ka balay nga ₱2,000,000 (mga $31,900 / €28,500), mga ₱1,000 (mga $16 / €14) kana matag tuig para sa flood ug typhoon ug ₱2,000 (mga $32 / €28) para sa earthquake sa minimum, ug mas dako sa coastal ug flood prone nga mga lugar, diin gipresyohan sa mga insurer ang exposure. Wala pay 20% sa mga panimalay ang adunay bisan asa niini, sumala sa datos sa Insurance Commission nga gikutlo sa ulahing bahin sa 2025.
Para sa usa ka buyer, ang premium usa ka signal sama nga kini usa ka gasto. Ang usa ka quote nga taas ang balik, nga adunay mga exclusion o mas dako nga deductible para sa usa ka piho nga kalye, mao ang pagbasa sa underwriter sa risgo nga wala gihisgotan sa seller. Ang among giya sa home insurance sa Pilipinas nagpasabot kon unsa ang wala maapil sa standard fire policy ug unsaon pagdugang ang typhoon, flood ug earthquake extensions, ug ang among giya sa condo insurance naghisgot sa pagbahin tali sa policy sa building ug sa policy sa tag-iya sa unit.
Coastal property
Ang usa ka beach lot nagdala sa sea level trend, storm surge ug erosion dugang sa mga balaod nga naglimite na niini: ang foreshore iya sa Estado ug ang usa ka public easement moagi daplin sa baybayon sulod sa matag titulado nga lote, mao nga ang bahin sa parcel magpabilin nga abli ug walay tukod. Ang among giya sa beachfront property naglista sa mga gilapdon sa easement ug sa mga balaod sa foreshore, ug ang among giya sa usa ka vacation home sa Pilipinas nagtimbang sa baybayon batok sa ridge ug sa kabukiran bahin sa pagmentinar ug risgo. Ang mga praktikal nga check parehas ra sa bisan unsang lote, dugang og duha: ang storm surge ug erosion history sa maong bahin sa baybayon gikan sa barangay ug sa municipal disaster office, ug usa ka pangutana sa resale nga dali makalimtan, nga mao kon kinsa ang mopalit sa usa ka shoreline lot sa napulo'g lima ka tuig ug sa unsang mga termino.
Unsaon pagbutang niini sa usa ka desisyon
Buhata ang hazard check sa dili pa ang viewing, dili human. Pangayoa sa seller ang flood history nga sinulat, ug ikumpara kini sa gisulti sa mga silingan. Pagkuha og insurance quote para sa piho nga address sa dili pa ang offer ug isipa ang pagbalibad o ang taas kaayo nga premium isip impormasyon. Isipa ang elevation, ang drainage ug ang kasaligan nga suplay sa kuryente isip mga feature nga angay bayran, tungod kay gibuhat kana sa mga tenant, ug ang usa ka condo nga nakalahutay sa bagyo apan nalunod sa tubig ang mga kalye sa palibot niini mawad-an gihapon sa tenant. Ug para sa long hold, pilia ang yuta nga wala magkaunlod: ang mga numero sa gobyerno bahin sa subsidence mao ang labing klaro nga climate signal sa Philippine property, ug ang labing panagsa hisgotan sa showroom.
Kini nga artikulo kinatibuk-ang impormasyon, dili investment advice. Ang mga numero gikan sa mga source nga gihisgotan sumala sa Oktubre 2026; ang mga kondisyon sa hazard ug insurance piho sa matag address, mao nga susiha kini para sa property nga imong gikonsiderar.
Kataposang gi-update niadtong 14 Oktubre 2026.
Banabana lang ang mga conversion sa dollar ug euro, sa ₱62.8 matag US dollar ug ₱70.2 matag euro (ECB reference rates, 2026-10-13).
Mga kasagarang pangutana
Naapektohan na ba sa climate change ang presyo sa mga property sa Pilipinas?
Ang labing klaro nga nasukod nga kausaban pisikal, dili sa presyo: ang climate assessment sa gobyerno sa 2024 National Adaptation Plan nag-ingon nga ang pagsaka sa sea level sa Manila mga 2.6 centimeters matag tuig, kadaghanan gikan sa land subsidence, ug ang usa ka metro nga pagsaka makaapekto og 7,000 square kilometers ug 1.8 million ka tawo. Wala kami mag-publish og flood discount, tungod kay dili kini mabulag sa mga presyo sa listing, apan ang mga buyer nag-check na karon sa mga hazard map ug ang mga insurer nagpresyo sa exposure sa matag address.
Unsaon nako pag-check ang flood ug hazard risk sa dili pa mopalit og property?
Gamita ang HazardHunterPH gikan sa DOST ug PHIVOLCS, nga naghimo og flood, landslide ug earthquake assessment para sa eksaktong address o pin, ug ang Project NOAH, nga nagpakita sa modeled flood depth para sa 5 year, 25 year ug 100 year nga ulan. Dayon pangutan-a ang barangay ug ang mga silingan bahin sa kataposang tulo ka bagyo, pangayoa sa seller ang flood history nga sinulat, ug pagkuha og insurance quote para sa piho nga address sa dili pa mohimo og offer.
Maayo pa ba nga investment ang mga beachfront property sa Pilipinas?
Nagdala kini sa sea level trend, storm surge ug erosion dugang sa mga balaod nga naglimite na niini: ang foreshore iya sa Estado ug ang usa ka public easement moagi daplin sa baybayon sulod sa matag titulado nga lote. Sa dili pa mopalit, kuhaa ang storm surge ug erosion history sa maong bahin sa baybayon gikan sa barangay ug sa municipal disaster office, kumpirmaha ang easement sa survey, ug hunahunaa kon kinsa ang mopalit sa usa ka shoreline lot sa napulo'g lima ka tuig.
Pila ang gasto sa flood ug typhoon insurance sa Pilipinas?
Ang minimum nga tinuig nga rates sa Insurance Commission mao ang 0.05% sa sum insured para sa typhoon ug flood cover ug 0.10% para sa earthquake cover, nga adunay mandatory nga 2% deductible sa mga typhoon ug flood claim, mao nga ang usa ka balay nga ₱2,000,000 (mga $31,900 / €28,500) mobayad og mga ₱1,000 ug ₱2,000 (mga $16 hangtod $32 / €14 hangtod €28) matag tuig sa minimum. Mas taas ang rates sa coastal ug flood prone nga mga lugar, ug wala pay 20% sa mga panimalay ang adunay bisan unsang disaster cover.
Browse properties on BalayHub
See all listings →
Read next
Rent or Buy in Metro Manila 2026: The Break-even Math
Rent or buy in Metro Manila: a one bedroom rents for ₱25,000 and sells for ₱7.7M. The monthly cost of owning, the break even growth rate and the horizon.
Land Title Annotations Philippines: What Each Entry Means
Land title annotations Philippines buyers must read: mortgage, lis pendens, adverse claim, levy, easement and the Rule 74 entry, and how to clear each one.
RFO Condo vs Pre-Selling in the Philippines: Which to Buy
RFO condo vs pre-selling: cash needed now or stretched over 24 to 48 months, construction risk, rent from month one, and the finished buildings by city.